
Austin gets hit hard. Hail in spring, straight-line winds during summer storms, and the occasional ice event in winter. By the time you're reading this, you've probably either just been through a storm or you're staring up at your roof wondering if it's about to be a problem.
Here is the honest version of what every Austin homeowner should know after a storm: when a repair is enough, when you need a replacement, and how to handle the insurance side without getting taken advantage of.
First, do a careful look from the ground
Don't climb up there. Most roof injuries happen to homeowners and DIYers, not contractors. Walk the perimeter of your house and look for:
- Missing or visibly torn shingles. Even one or two is a sign there could be more.
- Granule buildup in your gutters or at the bottom of downspouts. A few granules is normal. Piles are not.
- Dents in metal flashing, vents, or gutters. If hail dented the metal, it almost certainly bruised the shingles.
- Cracked, lifted, or curled shingles, especially on the south and west sides. Those sides take the worst of Austin's UV and storm exposure.
- Daylight in the attic. Easy check, scary finding. Means a hole in the deck or a torn-back shingle.
- Stains on ceilings or upper-floor walls. Often a sign of an active or recently active leak.
If you find any of these signs, call a roofer for an inspection before you call your insurance company. A reputable roofer will tell you whether you have a real claim or just normal wear and tear. Filing a claim that doesn't pay out can still affect your premiums.
Worried after a recent storm? We do free, no-obligation roof inspections across greater Austin. We'll tell you the truth: repair, replace, or wait and watch.
Schedule a free inspectionRoof repair vs. replacement: how to tell in Austin
A repair is usually right when:
- The damage is contained to one area or one slope of the roof.
- Your roof is under 12 to 15 years old.
- The shingles in the damaged area can be matched (color, style, profile).
- There is no widespread granule loss or hail bruising across the rest of the roof.
A replacement is usually right when:
- You see hail bruising or impact marks across multiple slopes.
- The roof is 18+ years old, or near the end of its rated life.
- Multiple leaks have shown up, or one leak has come back after a repair.
- The decking under the shingles is soft, sagging, or has visible rot.
- Your insurance adjuster has totaled the roof. (More on that below.)
How long does a roof replacement take?
For a standard Austin home, the actual replacement is usually 1 to 2 days on the roof. From the day you sign to the day the crew shows up is typically 2 to 6 weeks, depending on material lead times, permit pulls, and how busy the trades are. After a major hail event, that timeline can stretch to 8 to 12 weeks because every roofer in town is booked.
The insurance side, in plain English
1. Document everything before you call
Photos and video of the exterior, attic, and any interior staining, dated. Save them somewhere you can access from your phone. The more documentation you have when the adjuster shows up, the smoother the process goes.
2. Get an inspection from a real local roofer
Before the adjuster comes out, have a local roofer walk the roof and write up what they find. The good ones do this for free. They'll tell you whether you have a legitimate claim and roughly what scope they expect the carrier to approve.
3. Beware the door-knockers
After every major hail event in Austin, out-of-town storm chasers show up offering "free roofs" and "no out-of-pocket" promises. Many of them disappear before warranty issues come up. Hire a local roofer who lives in Austin, not someone working out of a hotel room.
4. Know what's covered
Most homeowners' policies in Texas cover wind and hail damage. They generally do not cover normal wear, age, or improper installation.
Some policies have separate, higher deductibles specifically for wind and hail (often 1 to 2 percent of dwelling coverage, and higher on some policies). Read your declarations page before the adjuster arrives.
5. RCV vs. ACV matters
Replacement cost value (RCV) policies pay to replace your roof with new materials. Actual cash value (ACV) policies pay only the depreciated value.
If your policy is ACV and your roof is 20 years old, you might end up with a small check and a big bill. Worth confirming now, before a storm.
What hail has to do to damage a roof
Not every hailstorm damages a roof, and knowing the rough thresholds saves you filing a claim that will not pay.
- Under three quarters of an inch. Rarely damages asphalt shingles. It can still dent soft metals: gutters, downspouts, vents, and an aluminium garage door.
- One inch, about a quarter. This is roughly where asphalt shingles start to bruise. A bruise is a soft spot where the mat has fractured under the granules, and you usually cannot see it from the ground.
- An inch and a half and up. Damage is normally obvious and widespread, and a full replacement is the likely outcome.
The important part: hail damage is mostly invisible from the driveway. Bruising does not look like a hole. It looks like nothing, until the granules wash off over the following year and the mat starts failing.
That is why the metal is worth checking. If hail dented your gutters and vent caps, it hit the shingles with the same force.
Central Texas hail season runs roughly March through June, with May the worst month most years. If a storm came through your neighbourhood and you did nothing at the time, it is still worth an inspection.
The numbers, roughly
| Item | Typical in the Austin area |
|---|---|
| Full roof replacement, architectural shingle | $11,000 to $18,000 |
| Standing-seam metal roof | $25,000 to $45,000 |
| Localised storm repair, one slope | $800 to $3,500 |
| Decking replacement found during tear-off | $70 to $120 per sheet |
| Wind and hail deductible | Often 1 to 2 percent of dwelling coverage |
| On a $400,000 dwelling limit, that is | $4,000 to $8,000 out of pocket |
| Roof inspection | Free, from any roofer worth hiring |
The deductible line is the one that surprises people. A wind and hail deductible is frequently separate from, and much larger than, the flat deductible on the rest of the policy.
If hail is replacing your roof, it is also the cheapest time to move up to impact-rated shingles. Our Class 4 shingles guide explains what the upgrade costs and how the Texas insurance discount works.
The deductible promise is illegal in Texas
This is the single most useful thing on this page, so we will be blunt about it.
After every hail event, somebody knocks on doors offering to "cover your deductible", "waive your deductible", or get you a "free roof with no out of pocket". Texas law makes it illegal for a contractor to pay, waive, rebate or absorb any part of your insurance deductible.
So the offer is not generosity and it is not a discount. It means one of three things, all bad for you:
- They are inflating the invoice to the carrier to cover the gap, which is insurance fraud, and your name is on the claim.
- They are cutting the scope so the job costs what the claim paid minus your deductible, and you get a cheaper roof than the one you were assessed for.
- They will simply bill you for it later, once the work is done and your leverage is gone.
A contractor willing to break that law on day one is telling you what they will do when a warranty claim shows up in year three. Treat it as the clearest disqualifier there is.
Wind damage is a separate thing
Austin gets straight-line winds through summer storms, and wind damage behaves differently to hail. It concentrates at edges and ridges rather than spreading evenly across the field of the roof, so it is often confined to one slope or one run of ridge cap.
Wind also lifts shingles without removing them. A shingle that sealed, lifted, and set back down looks perfectly normal and is no longer bonded, which means the next storm takes it. This is a common finding on a roof the homeowner was sure was fine.
Both wind and hail are normally covered on a Texas homeowners policy. Wear, age and poor installation are not.
Timing, and why waiting costs you
Most policies require you to report a loss promptly, and carriers push back hard on claims filed a year or more after the storm that caused them. The longer you wait, the easier it is for an adjuster to attribute the damage to age, wear, or a different weather event that was not covered.
There is a practical reason to move early too. After a major hail event every roofer in the region books out, and a two to six week lead time becomes eight to twelve. The homeowners who called the week of the storm get their roofs before the ones who waited for the queue to clear.
What you should not do is let anyone start work before the adjuster has inspected. The unrepaired damage is the evidence.
What to ask any Austin roofer before you sign
- Are you locally based and have you been in Austin for at least a few years?
- Are you licensed and insured? Can I see proof of liability and workers' comp?
- What underlayment do you use? What about ice and water shield in the valleys?
- Will you pull the permit, or are you asking me to?
- What's the warranty on labor and on materials, in writing?
- Will you replace damaged decking and flashing if you find rot under the shingles? (The honest answer is "yes, on a per-board upcharge that we'll show you before installing.")
- Who picks up the trash and the nails? (Should be them. With a magnetic sweeper.)
Should you wait or replace now?
If your roof is doing its job and not actively leaking, you can usually wait until you have a storm event that triggers an insurance claim or until the roof reaches end-of-life. Don't replace a perfectly functioning roof out of fear.
But also don't wait through three obvious leaks hoping it'll stop on its own. The damage to drywall, framing, and insulation usually costs more than the new roof would have.
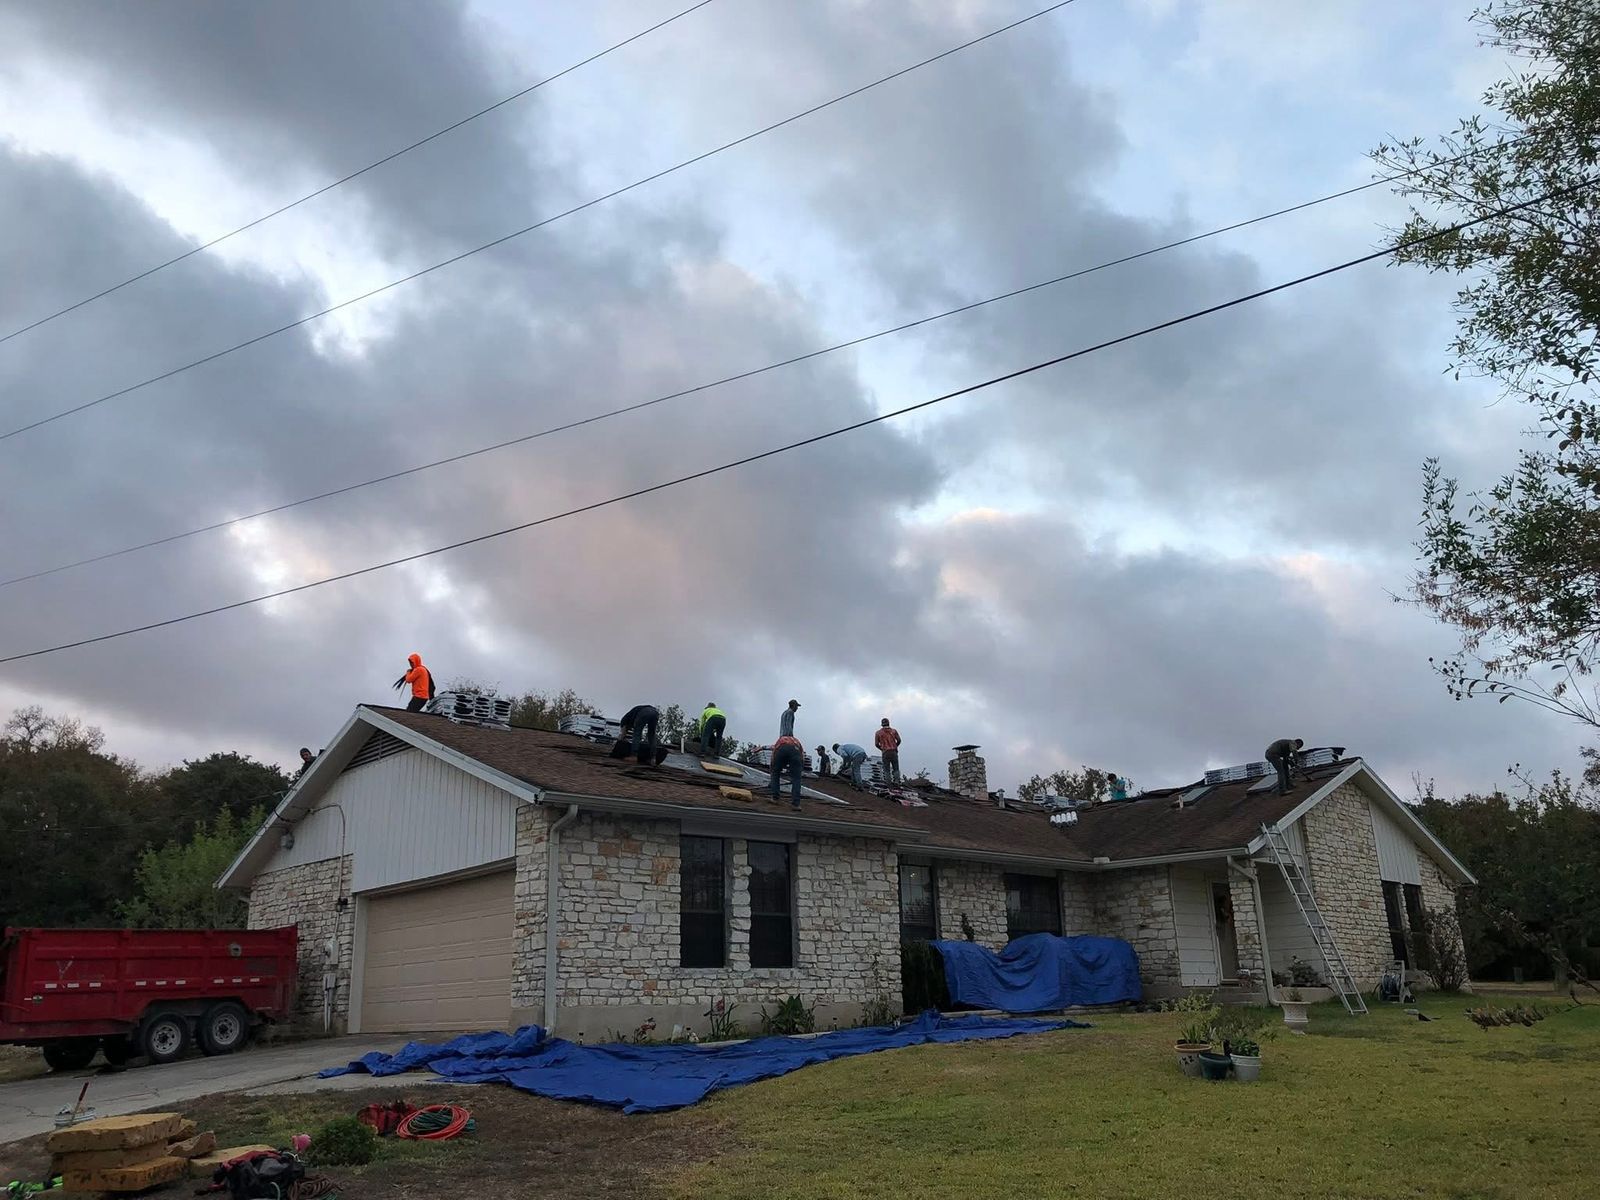
Not sure where you stand? A free, no-obligation inspection takes about 30 minutes and you'll get an honest answer either way. Call or text anytime.
Get a free inspectionSee our Austin roofing page for the roofs we install and recent replacements.
Storm damage questions, answered
Does insurance cover storm damage to a roof in Austin?
Wind and hail damage is normally covered on a Texas homeowners policy. Wear, age and poor installation are not. Many Texas policies carry a separate wind and hail deductible, often 1 to 2 percent of the dwelling coverage rather than a flat amount, so on a $400,000 dwelling limit you could be looking at $4,000 to $8,000 out of pocket. Check your declarations page before the adjuster arrives.
How do I know if my roof has hail damage?
Mostly you cannot tell from the ground, which is the problem. Hail bruising fractures the shingle mat under the granules and does not look like a hole. The reliable ground-level tell is soft metal: if hail dented your gutters, downspouts or vent caps, it hit the shingles with the same force. Granule piles at the bottom of downspouts are the other sign. Get a free inspection rather than climbing up.
Can a contractor cover my insurance deductible?
No. Texas law makes it illegal for a contractor to pay, waive, rebate or absorb any part of your insurance deductible. If somebody offers a free roof with no out of pocket, they are either inflating the invoice to your carrier, which is fraud on a claim with your name on it, cutting scope so you get a cheaper roof than you were assessed for, or planning to bill you later. Treat the offer as a disqualifier.
Should I repair or replace a storm-damaged roof?
Repair when the damage is confined to one area or slope, the roof is under 12 to 15 years old, and the shingles can be matched. Replace when there is bruising across multiple slopes, the roof is 18 years or older, leaks have recurred, the decking is soft, or the adjuster has totalled it. A localised repair runs $800 to $3,500 against $11,000 to $18,000 for a shingle replacement.
How big does hail have to be to damage a roof?
Roughly an inch, about a quarter coin, is where asphalt shingles start to bruise. Below three quarters of an inch, hail rarely harms shingles but can still dent gutters, vents and aluminium. At an inch and a half and above, damage is usually widespread and replacement is the likely outcome. Central Texas hail season runs March through June, with May typically the worst.
How long do I have to file a storm damage claim in Texas?
Report it promptly. Most policies require prompt notice of a loss, and carriers push back on claims filed a year or more after the storm, because the longer you wait the easier it is to attribute damage to age or a different uncovered event. If a storm came through and you did nothing at the time, get it inspected now rather than assuming the window has closed.
Who does storm damage roof repair in Austin?
JB Contracting ATX does free storm damage inspections across greater Austin, documents what we find with photographs, and meets your adjuster at the house so somebody is there who can point at the damage. We are family owned, licensed and insured, and rated 5.0 on Google. If your roof does not need replacing, we will tell you that.
Should I use the roofer who knocked on my door after the storm?
Usually not. After every major Central Texas hail event, out-of-town crews arrive, work the neighbourhood, and leave before any warranty claim can surface. Hire somebody who lives here and will still be here in five years, ask for their Texas address, and check reviews that predate the storm. Anyone offering to cover your deductible has already disqualified themselves.
Weighing a metal roof against new shingles? See our comparison of metal roofs vs shingles in Austin, with costs, hail, insurance and HOA rules.
Sources
- Texas Business and Commerce Code, Section 27.02, Texas Legislature: makes it an offense for a seller paid from an insurance claim to pay, waive, absorb or rebate the deductible.
- Roofing discounts, Texas Department of Insurance: impact-resistant (UL 2218) roofing can qualify for a premium discount, and each insurer sets its own amount.
Prices on this page come from our own 2026 Austin-area quotes. Rules change, so we check which ones apply to your address before every build. New to a term? See our plain-English glossary.